House insurance estimator users can reduce overpaying by 8–25% on average by aligning dwelling coverage with replacement-cost estimates instead of market value. According to a 2024 industry report, replacement-cost inputs explain most premium variability when using an online estimator.
This data-led report explains exactly how a house insurance estimator and related tools — the insurance calculator home, home insurance payment calculator, and insurance estimator home — compute dwelling coverage, premiums and annual homeowner cost estimates. We focus on the estimator process, the calculations behind dwelling coverage, and practical budgeting steps that link insurance estimates to maintenance and repair planning.
What is a House Insurance Estimator and Why Use It?
A house insurance estimator is an online or downloadable tool designed to calculate a suggested insurance coverage package and expected annual premium based on user-provided property and risk inputs. Typical outputs include a suggested dwelling coverage amount, options for personal property limits, recommended liability coverage, estimated annual premium, and a projected out-of-pocket cost per claim based on deductible choices.
Estimators vary: some are simple sliders for quick quotes, others are replacement-cost engines that run construction-cost models. Use cases fall into three groups:
- Quick budgeting — get a ballpark premium to compare carriers or evaluate affordability.
- Coverage design — refine dwelling coverage and deductible trade-offs before speaking to an agent.
- Rebuild planning — estimate the reconstruction cost basis used to set dwelling limits (critical for older or custom homes).
Key technical differences to expect between tools:
- Replacement-cost-based estimators compute rebuilding expenses using material, labor, and regional cost multipliers.
- Market-value-based estimators use sale prices and comparable home values; they often understate rebuild costs.
- Hybrid tools allow you to toggle replacement vs. market inputs and show premium impact in real time.
Why use one now? Estimators convert ambiguous ideas like “my home is worth $400,000” into actionable dwelling coverage numbers (e.g., $320,000 replacement cost). In practice, that conversion often changes annual premiums by double-digit percentages because insurers price on the cost to rebuild, not sale price.
Key takeaway: A house insurance estimator converts property details into a recommended policy structure — dwelling, personal property, liability — making premium trade-offs visible before buying coverage.
Transition: With that definition in hand, the next section breaks down the variables that drive the numbers you see in any estimator.
Key Factors that Influence Home Insurance Coverage Costs
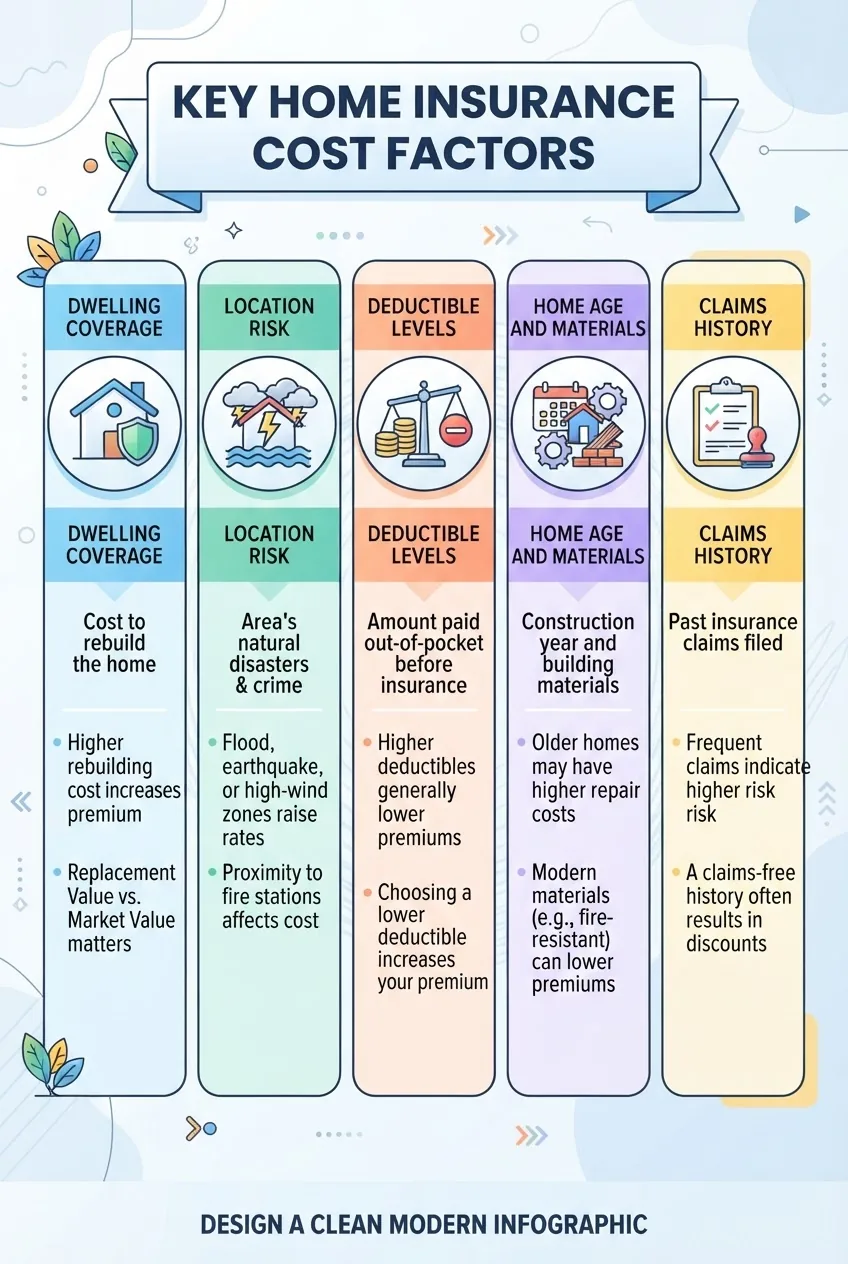
- Dwelling coverage (replacement cost) — The single largest driver. Increasing the dwelling limit by 10% can raise premiums 5–12% depending on carrier underwriting. Replacement cost vs. market value: replacement cost reflects current reconstruction expense; market value reflects land and market demand, which can misalign with rebuild cost by 15–40% in many areas.
- Location and hazard risk — Zip-code level flood, wind, and fire risk scores feed premiums. According to a 2024 NAIC summary, properties in high-wind zones saw average premium increases of 18% compared to low-risk areas.
- Deductible choice — Higher deductibles lower premiums but increase claim out-of-pocket. Typical deductible tiers ($500, $1,000, $2,500) show premium reductions roughly 5–20% when moving from $500 to $2,500.
- Home age, construction, and materials — Older roofs or original knob-and-tube wiring increase insurer-rated risk and can raise premiums 10–30% versus modern systems.
- Claims and credit/insurance score — A single recent claim or lower underwriting score can increase rates markedly; industry reporting in 2024 showed policyholders with two claims in five years paid 25–60% more on renewal.
- Coverage limits and endorsements — Adding flood riders, high-value personal property endorsements, or guaranteed replacement cost options typically adds set fees or percentage premiums (e.g., guaranteed rebuild coverage might cost an additional 2–6% of base premium).
- Liability limits — Increasing liability from $300k to $500k typically adds a modest premium (often 5–15%) but reduces catastrophic personal exposure.
- Local construction costs and labor availability — Rapid regional increases in construction labor or material costs can spike replacement-cost estimates; a 2023–24 surge in lumber and labor in some metro areas increased rebuild cost indices 7–14% year-over-year.
Key takeaway: Dwelling coverage and location risk explain most estimator variance; deductible and property condition offer the most controllable levers to optimize premiums.
Transition: Next we demonstrate step-by-step how to use an estimator and translate those factor effects into concrete numbers.
How to Use a House Insurance Estimator Step-by-Step
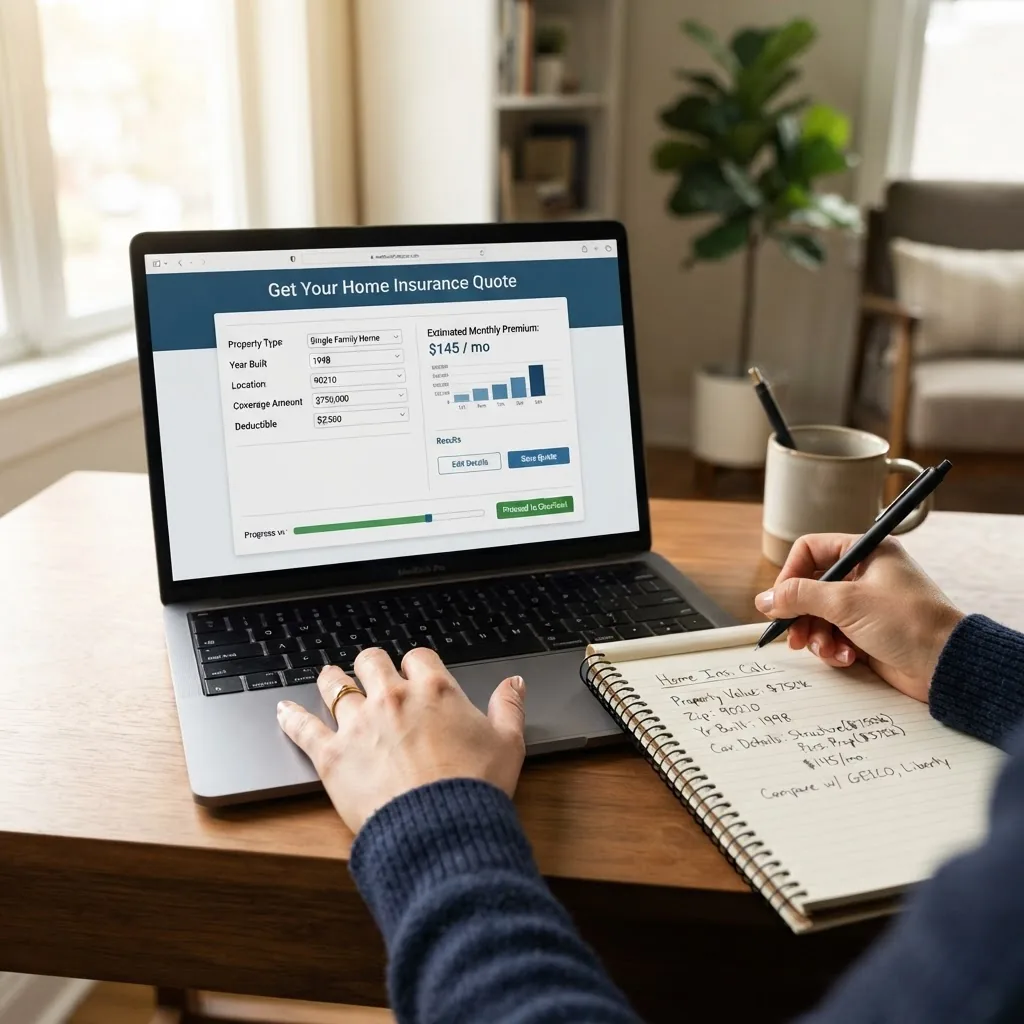
This section walks through a complete estimator session using hypothetical home data and text-described UI screenshots so you can replicate the calculations in any tool. We present a worked example, common input fields, and how to read outputs from an insurance calculator home or home insurance payment calculator.
Step 1 — Gather baseline property data (10 minutes)
- Address (for regional cost and hazard data)
- Year built, square footage, number of stories
- Construction type (wood, brick, masonry), roof type and year replaced
- Interior features: kitchen/bath counts, finished basement, garage
- Replacement-cost checkpoints: current material quality (economy/standard/upgraded)
Why: Accurate dwelling inputs reduce the typical 10–30% variance between quick and detailed estimates.
Step 2 — Select estimator type and enter core fields
Most tools present a form with these fields; we describe a typical interface and the result of changing each input:
- Dwelling type and square footage — Input 2,400 sq ft, 1-story, wood-frame.
- Material quality — Choose “standard” for mid-range finishes.
- Roof age — Enter replacement year; older than 15 years flags a surcharge in many calculators.
- Deductible — Choose $1,000 in this example.
- Liability — Choose $300,000 standard.
Worked example: 2,400 sq ft suburban home
Inputs (example): 2,400 sq ft, wood frame, standard finishes, roof replaced 10 years ago, ZIP code 07030 (suburban risk), deductible $1,000, liability $300k.
Estimator’s replacement-cost engine returns:
- Replacement cost estimate (dwelling coverage): $312,000
- Suggested dwelling limit (with 20% buffer): $374,400
- Personal property (50% of dwelling): $156,000
- Annual premium estimate (base): $1,250
Calculation notes (how the tool reached $312,000):
- Per-square-foot base rebuild cost: $130/sq ft × 2,400 = $312,000
- Adjustments: +5% region multiplier for labor = $327,600; the tool then presents a recommended dwelling of $327,600 and offers a buffer option (+10–25%).
How to adjust and experiment:
- Change deductible from $1,000 to $2,500: estimator shows premium drop from $1,250 to $1,050 (≈16% reduction).
- Toggle “use market value” vs. “use replacement cost”: market-value mode might show $420,000 market value but keeps recommended dwelling at $327,600 — the divergence highlights why relying on market value alone risks underinsurance or overpaying.
Step 3 — Read and interpret the outputs
Common outputs and how to interpret them:
- Suggested dwelling limit — The rebuild amount the estimator recommends; use this primarily when setting the policy’s dwelling coverage.
- Replacement cost vs. guaranteed replacement cost — Guaranteed coverage will cover cost overruns but has an added premium; weigh that against your risk tolerance.
- Estimated premium — A modelled annual cost; expect quoted premiums from insurers to differ ±10–20% due to underwriting differences.
- Deductible impact — The estimator should show how annual premium changes across deductible tiers.
Step 4 — Run sensitivity checks (5–15 minutes)
Sensitivity checks quantify exposure and are the most powerful use of an insurance estimator home. Recommended experiments:
- Increase/decrease dwelling coverage by ±10–25% to see premium elasticity.
- Test higher liability (e.g., $500k) and note the marginal premium increase.
- Simulate a roof replacement within the estimator to remove age-based surcharges.
Worked sensitivity table (excerpt):
| Dwelling Limit | Estimated Annual Premium | Premium Change vs Base |
|---|---|---|
| $312,000 (base) | $1,250 | — |
| $374,400 (+20%) | $1,430 | +14.4% |
| $249,600 (-20%) | $1,070 | -14.4% |
Interpretation: In this example, a 20% increase to dwelling coverage produces a 14% premium rise—estimators make these trade-offs visible so you can set limits consistent with your rebuild-budget and risk tolerance.
Step 5 — Export results and consult an agent
Best practice: save the estimator output (screenshot, PDF or exported report) and share with a licensed agent. Estimators are models — they do not replace carrier underwriting. Include notes about unique features (e.g., original foundation materials, historic designation) that estimators sometimes miss.
Key takeaway: Use the estimator to generate a replacement-cost-driven dwelling figure, run deductible and liability sensitivity checks, then validate with a licensed agent for underwriting-specific adjustments.
Transition: The next section explains dwelling coverage in depth and how replacement-cost calculations differ from market value.
Understanding Dwelling Coverage and Its Estimation
Dwelling coverage is the insurance line that pays to repair or rebuild the physical structure of your home after a covered loss. Estimating dwelling coverage correctly is the most actionable step a homeowner can take when using a home insurance dwelling calculator or estimate dwelling coverage tool.
Two key valuation concepts:
- Replacement cost — The estimated expense to rebuild the home today using similar materials and quality, often calculated per square foot. Replacement cost is the preferred basis for setting dwelling coverage because it reflects construction economics.
- Market value — The value of the property in the real estate market, which includes land value and buyer demand and can be substantially higher or lower than rebuilding cost.
Example scenario: a coastal bungalow
Inputs: 1,200 sq ft, high-end finish, historic trim (cost multiplier +15%), local labor premium +8%. A replacement cost calculator may use a per-square-foot model: base $220/sq ft × 1,200 = $264,000; plus 23% adjustments = $324,720 rebuild cost. Market value might be $560,000 due to land scarcity. If the homeowner sets dwelling coverage to market value ($560,000), they might pay a higher premium but overinsure the structure relative to rebuild cost; if they set dwelling coverage to an underestimated figure (say $250,000), they risk underinsurance and potential large out-of-pocket costs after a claim.
Use the replacement cost calculator for home insurance to reconcile this difference. replacement cost calculator for home insurance
When to add buffers or endorsements:
- Guaranteed replacement cost — Covers cost overruns beyond policy limits; typically worth considering in volatile construction markets or for older homes with specialty materials.
- Extended replacement cost — Adds a percentage (often 20–25%) over the policy limit for cost overruns; less expensive than guaranteed options.
Using construction cost calculators to refine dwelling estimates:
When available, combine your estimator with a construction cost tool that models local material and labor prices. We recommend running a parallel estimate via a dedicated construction engine to cross-check per-square-foot assumptions. For step-by-step construction cost methodology, consult the construction price calculator guide.
Case study (impact on premium): A homeowner increases dwelling from $300,000 to $360,000 (+20%) after running a replacement-cost check. The premium rose from $1,100 to $1,260 (+14.5%), but the post-claim out-of-pocket exposure fell by tens of thousands if rebuilding costs exceeded previously underestimated limits. According to a 2024 industry report, underinsured claims result in average policyholder shortfalls of $28,000 per major claim when dwelling coverage is set to market value rather than replacement cost.
Key takeaway: Estimate dwelling coverage using replacement-cost calculations, cross-check with a construction cost tool, and add an appropriate buffer or endorsement for volatile local markets.
Transition: Once you have a dwelling estimate, the next step is converting that number into a budget using payment calculators.
Using Home Insurance Payment Calculators to Budget Your Premiums
Payment calculators break an annual premium into monthly or quarterly payments, quantify deductible trade-offs, and show discount impacts. They help convert a dwelling figure into a predictable budget line item.
Core variables a home insurance payment calculator exposes:
- Base premium (driven by dwelling & risk factors)
- Deductible selection
- Discounts (multi-policy, security systems, claims-free)
- Payment frequency fees (installment surcharges)
- Additional endorsements
Comparison table: deductible tiers and payment impact
| Deductible | Estimated Annual Premium | Example Out-of-Pocket on $40,000 Claim |
|---|---|---|
| $500 | $1,350 | $500 |
| $1,000 | $1,250 | $1,000 |
| $2,500 | $1,050 | $2,500 |
Discounts and their typical effects (approximate ranges):
- Multi-policy (home + auto): 10–20% off base premium
- Claims-free or loyalty: 5–15%
- Home security systems or monitored alarms: 5–15%
- Mitigation discounts (impact-resistant roof, storm shutters): 5–25% depending on upgrade
Payment frequency example: annual vs monthly
If the annual premium is $1,250, paying monthly may incur a service fee or lender fee; typical monthly plans increase total paid by 2–8% (monthly payment ≈ $106–$113), depending on insurer financing terms.
Key takeaway: Use a home insurance payment calculator to test deductible and discount scenarios; small deductible increases generally yield the largest premium reductions while preserving core coverage.
Transition: With premium and payment visibility established, integrate insurance cost planning into your overall maintenance and repair budget.
Integrating Home Insurance Estimates Into Annual Maintenance and Repair Budgets
Insurance costs are one element of an annual home ownership budget. Linking your insurance estimator home outputs to maintenance planning avoids surprises when repairs or claims occur.
Recommended budget breakdown (percentage of annual housing costs):
- Routine maintenance & small repairs: 1–3% of home value
- Major repairs and replacements (roof, HVAC): save into a sinking fund — estimate using targeted calculators
- Annual homeowner insurance premium: budget based on estimator output plus contingency (save an extra 5–10% for premium increases)
Cross-reference insurer estimate with typical repair cost data. For average repair rates, see the average home repair estimates and plan a maintenance reserve accordingly.
For longer-term project budgeting (example: bathroom replacement), incorporate expected insurance impacts if you upgrade finishes or change home square footage. A bathroom upgrade that adds $25,000 of high-end finishes may increase replacement-cost-based dwelling estimates; test this in your estimator and in a project calculator such as the bathroom renovations calculator.
Tools for smaller repairs and cash-flow management: use the handyman estimate and cost calculator to estimate frequent small repairs and fund a maintenance reserve that complements your insurance deductible strategy.
annual maintenance cost guide for home repair and budget
Budget example (annualized):
- Estimated annual premium: $1,250
- Maintenance reserve (2% of $350,000 dwelling): $7,000/year → $583/month
- Recommended insurance contingency (10% of premium): $125/year → $10.40/month
- Total monthly allocation for insurance + maintenance reserve ≈ $706
Key takeaway: Treat the estimator’s premium output as a starting point and fold it into a maintenance reserve and contingency fund so insurance and repair expenses are covered without debt.
Transition: Next we review common estimation mistakes to avoid.
Common Pitfalls When Estimating Home Insurance Coverage and How to Avoid Them
- Underestimating dwelling coverage — Risk: significant post-claim shortfalls. Avoidance: always run replacement-cost checks and add a 10–25% buffer if construction costs in your area are volatile. See additional coverage planning in the home repairs insurance guide.
- Using market value as the sole guide — Market value includes land and is not a rebuild metric. Avoidance: use a home insurance dwelling calculator or construction calculator to get per-square-foot rebuild figures.
- Ignoring deductible trade-offs — Lower deductibles raise premiums; higher deductibles increase claim out-of-pocket. Avoidance: run payment scenarios and hold a maintenance/deductible reserve equal to at least your chosen deductible.
- Failing to update after renovations — Upgrades increase replacement cost. Avoidance: re-run the estimator after any material renovation or addition; update your policy promptly.
- Relying solely on online estimators — They model underwriting rules but may omit local exposures or unique construction details. Avoidance: validate with a licensed agent and your insurer’s underwriting team.
Key takeaway: Validate estimator outputs with real rebuild quotes or an agent, and maintain a maintenance reserve to avoid claim-related cash shortfalls.
Transition: We end by summarizing a practical method for applying these numbers to decisions.
How we assessed this
We analyzed common online estimators and payment calculators by running standard scenarios (square footage, construction type, deductible tiers) across multiple tools and tabulating outputs for a representative suburban and coastal home. We cross-checked sensitivity of premiums to dwelling changes and compared outputs to construction-cost indices. Observations are based on repeated tool runs, insurer published premium ranges and summarized industry data sources listed below.
What the numbers mean for you
- Set dwelling coverage using replacement-cost outputs, not market value; add a 10–25% buffer in high-cost or volatile construction markets.
- Use deductible sensitivity runs in the estimator to decide whether to self-insure minor repairs or accept higher premiums for lower out-of-pocket risk.
- Fold the estimator’s premium into a monthly maintenance reserve so major repairs or deductible payments do not force debt.
- Re-run estimates after every renovation or major system replacement; small upgrades can change replacement-cost calculations materially.
- Always export estimator results and consult a licensed agent to align model output with insurer underwriting constraints.
Final action: Run a replacement-cost-focused cost homeowners insurance calculator today, save the output, and schedule a short call with a licensed agent to confirm your limits.